Drivers and vehicles
Lease or Buy a NEMT Vehicle in 2027? Costs, Terms, and Financing Compared
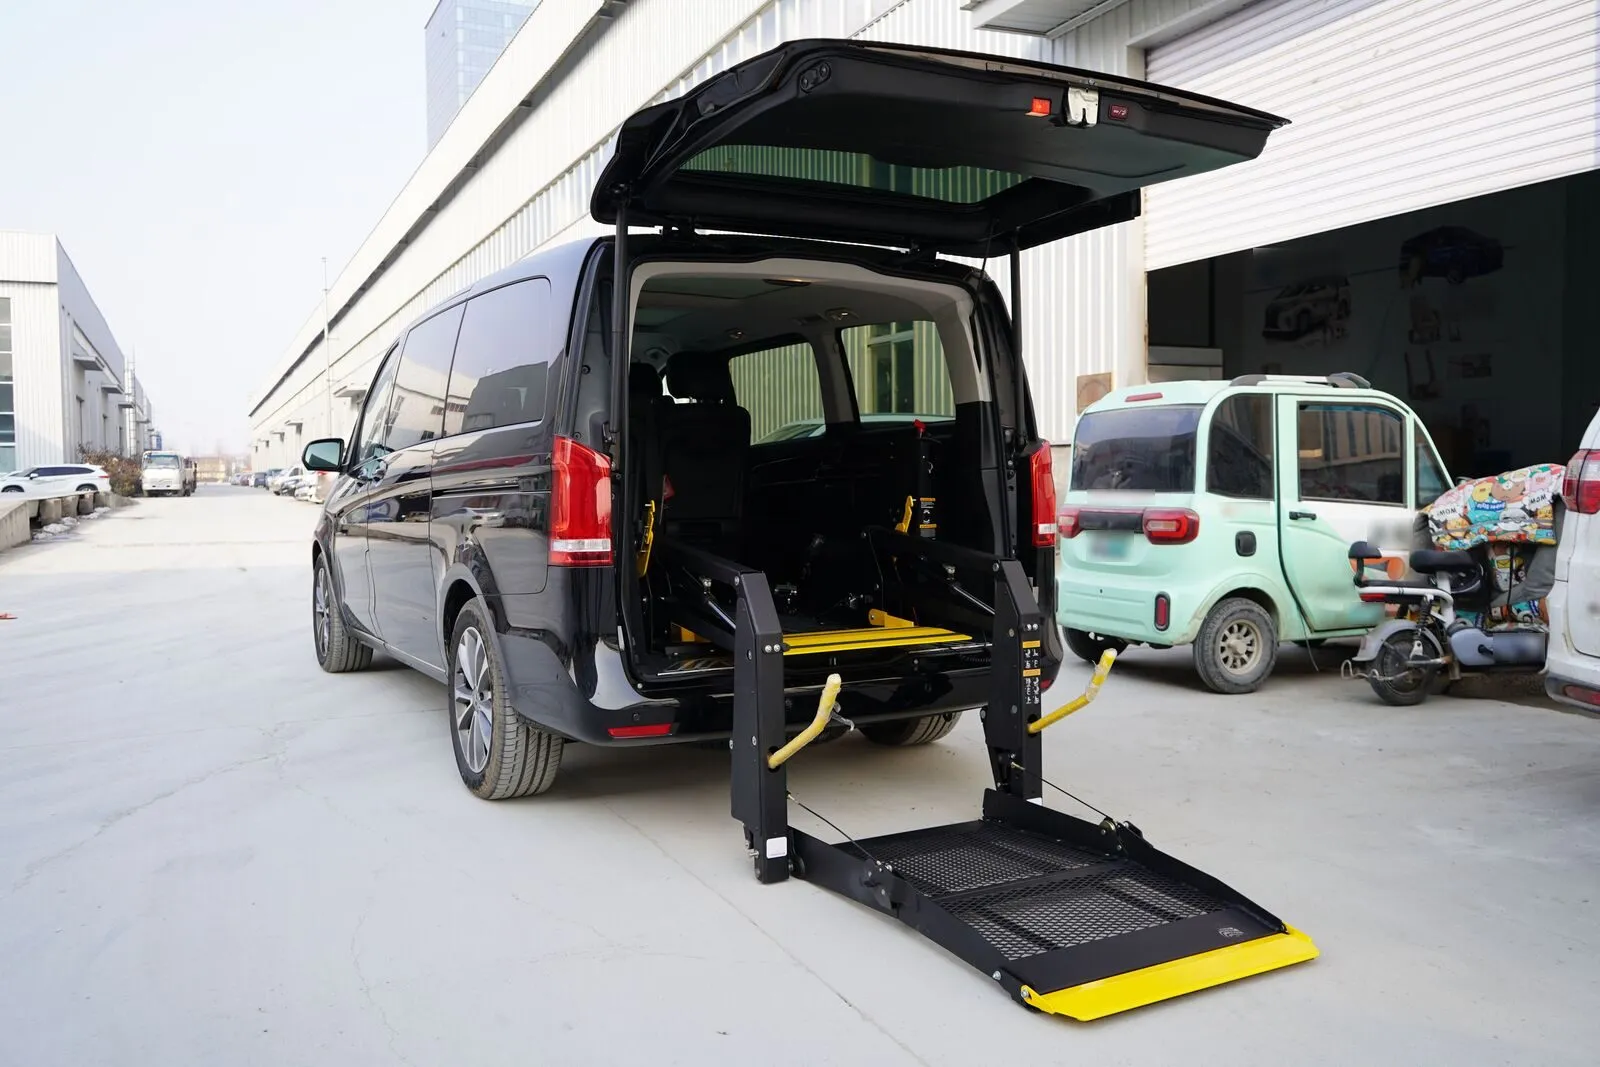
Buying a NEMT van with cash or a loan usually costs less over five years than leasing it. You keep the resale value, and you can often deduct the full cost in the first year. Leasing needs less cash up front, but mileage limits can make it expensive for a van that runs all day. Compare the five-year totals, not the monthly payments.
- Buying usually costs less over the life of a van, and leasing needs less cash up front, so compare the five-year totals, not the payments.
- Florida's transit program plans on 200,000 miles in five years for a converted minivan, so a lease mileage limit can cost thousands at turn-in.
- A van that carries riders for pay escapes the IRS car depreciation caps, and 100 percent first-year depreciation is back for vans acquired and placed in service after January 19, 2025.
- Leasing is allowed, but the van still needs your insurance, and Louisiana wants it registered in your company's name and inspected by the broker before its first trip.
- Match the loan or lease to the years the van will really work, and to broker age and mileage limits.
A wheelchair van is the biggest purchase most NEMT owners make, and there are three ways to pay for it: cash, a loan, or a lease. The monthly payment is the wrong way to compare them. A NEMT van runs up miles fast, it often carries a ramp or lift that a lease has to account for, and the IRS lets owners of vans that carry riders for pay write them off faster than ordinary cars.
This guide compares the three over five years, with real prices, loan math, and the IRS rules. For what a van costs to buy, see wheelchair van cost.
Lease, loan, or cash: how the options compare
The Small Business Administration’s lease-or-buy guidance sums up the trade. Leasing needs less cash or credit up front, sometimes includes maintenance, and its payments are typically tax deductible. Buying usually costs less over the asset’s life, lets you claim depreciation, and puts the asset on your balance sheet.
| Cash | Loan | Lease | |
|---|---|---|---|
| Money up front | The full price | A down payment | Less cash or credit than buying |
| Who owns the van | You | You, with the lender’s lien | The leasing company |
| Five-year cost | The price, minus what you sell the van for | The price plus interest, minus what you sell the van for | Every payment and fee, plus end-of-lease charges |
| Miles | No limit | No limit | Set in the lease, with a charge for each extra mile |
| Adding a lift or ramp | Your choice | Your choice | Only as the lease allows |
| Tax deduction | Depreciation, often 100 percent in year one | Depreciation plus the business share of interest | The business share of each payment |
| At the end | You keep or sell the van | You own it once it is paid off | You return it and pay any charges, or buy it out if the lease allows |
SBA also warns that loans cost more in fees and interest than paying cash, that cash spent on a van is cash you no longer have for operating costs, and that leaving a lease early can bring steep penalties. Brokers pay after the ride, not before: MTM Health’s provider agreement (January 1, 2023 version) pays properly submitted, uncontested invoices within 30 days of online submission. Keep enough cash for payroll and fuel whichever way you go. See NEMT cash flow and how long Medicaid takes to pay.
What each option costs over five years
Here is one van priced three ways. Florida’s transit vehicle contract lists an ADA ramp minivan at $69,476, plus $1,295 for a required seat and seat fabric, for $70,771 (order form effective February 20, 2025). The 9 percent loan rate is an example. The 13 percent rate is SBA’s cap for a variable 7(a) loan of $50,001 to $250,000: the base rate, here prime, plus 6 points, with prime at 7.00 percent in late September 2026.
| Five years of payments | Up front | Monthly | Interest | Total paid |
|---|---|---|---|---|
| Cash | $70,771.00 | $0 | $0 | $70,771.00 |
| Loan at 9 percent, 10 percent down | $7,077.10 | $1,322.18 | $15,636.90 | $86,407.90 |
| Loan at 13 percent, 10 percent down | $7,077.10 | $1,449.23 | $23,259.90 | $94,030.90 |
Whatever the van sells for at the end comes off the cash and loan totals. A leased van goes back to the lessor, so you get nothing back. That gives you a simple test for any lease offer. Add up every payment, fee, and end-of-lease charge the lease could bring. Then compare it with the loan’s total minus the van’s likely resale value.
| If the van resells after five years for | A five-year lease beats the 9 percent loan only if it costs less than | Which is a monthly average of |
|---|---|---|
| $0 | $86,407.90 | $1,440.13 |
| $10,000 | $76,407.90 | $1,273.47 |
| $20,000 | $66,407.90 | $1,106.80 |
Get a used-van price for the same model and mileage before you pick a resale number, and check it against used wheelchair van prices. Taxes mostly change the timing: an owner can often deduct the whole van in year one, while a lessee deducts each payment as it is made. Try your own numbers in the lease vs buy calculator and the wheelchair van loan calculator.
How mileage limits change the math
NEMT vans work hard. Florida’s transit program plans for a converted minivan to serve 5 years or 200,000 miles, and an unconverted van 4 years or 100,000 miles (useful life table, 2026). At that pace a converted van averages 40,000 miles a year.
A lease sets a mileage allowance and charges for every mile over it. That charge is in your contract, so the table below shows only the math. Plug in your own allowance and rate.
| Miles over the allowance after five years | At 10 cents a mile | At 20 cents a mile | At 30 cents a mile |
|---|---|---|---|
| 25,000 | $2,500 | $5,000 | $7,500 |
| 50,000 | $5,000 | $10,000 | $15,000 |
| 100,000 | $10,000 | $20,000 | $30,000 |
Mileage also runs out warranties early. Florida’s minivan contract (May 2020) warrants the base vehicle for 3 years or 36,000 miles, the powertrain for 5 years or 100,000 miles, and the ramp and body changes for 4 years with no mileage limit. At 40,000 miles a year, the base warranty ends in the first year whether you lease or buy. The contract’s order form prices extended coverage at $3,338 for 5 years or 100,000 miles, $4,303 for 5 years or 150,000 miles, and $5,802 for 7 years or 150,000 miles (February 20, 2025 order form).
Programs cap mileage and age too. Rhode Island accepts a van added after July 31, 2024 only if it is no more than four model years old with 150,000 miles or less at its first inspection, and retires it at 250,000 miles (policy effective October 31, 2024). A lease that ends before a limit like that is easier to plan around than a loan that outlasts the van. Ask each broker for its limits in writing, and see NEMT vehicle requirements and when to replace a NEMT vehicle.
Wheelchair conversions and equipment on a leased van
The ramp, lift, and tie-downs are part of what you pay for, so settle who owns them before you sign.
- Leasing a van that is already converted. The conversion belongs to the lessor with the van. Ask whether the lease treats wear on the ramp, lift, and tie-downs as normal or as damage you pay for at turn-in.
- Converting a van you lease. Get the lessor’s written consent first. For tax, IRS Publication 946 says you can depreciate capital improvements you make to leased property, and Publication 463 treats a major improvement to a vehicle as new 5-year property. Ask what happens to the equipment at the end: removed at your cost, left behind for free, or bought out.
- The federal paperwork. A shop that modifies a van for riders with disabilities, and in doing so makes a federal safety feature inoperative, must put a permanent label on the van and give you a document listing what changed (49 CFR 595.7). Keep it in the van file for your lessor and your broker.
Leasing does not change the federal accessibility rules. A private company in the business of carrying people that buys or leases a new van for demand response rides must get an accessible one, unless its service as a whole already gives wheelchair users equal service (49 CFR 37.103). See wheelchair van conversion for the conversion itself.
How leasing and buying are taxed
The IRS treats a van that carries riders for pay better than an ordinary car. From IRS Publications 946 and 463 (2025 editions):
| Buying, with cash or a loan | Leasing | |
|---|---|---|
| Main deduction | Depreciation, reported on Form 4562 and Schedule C line 13 for a sole owner | The business share of each lease payment, on Schedule C line 20a |
| First-year write-off | 100 percent special depreciation for qualified property acquired and placed in service after January 19, 2025 | None on the van. You deduct payments as you make them. |
| Section 179 | Up to $2,560,000 for tax years beginning in 2026, reduced once purchases top $4,090,000 | Not available on the van |
| Car depreciation caps | Do not apply: a vehicle used directly to carry people for pay is not a passenger automobile | The yearly inclusion amount for leased passenger automobiles worth more than $62,000 (2024 and 2025 leases) does not reach a van that carries riders for pay. You add an inclusion amount only in a year business use drops to 50 percent or less. |
| Interest | The business share of loan interest is deductible | Part of the lease payment |
| IRS mileage rate | Only if chosen in the first year, and never after Section 179, special depreciation, or MACRS on that van | Only if used for the whole lease |
| When you sell | Gain up to the depreciation taken is taxed as ordinary income | Nothing to sell |
A few rules carry the most weight:
- Listed property. Vehicles are listed property. You must use the van more than 50 percent for business to claim Section 179 or special depreciation, and if business use later drops to 50 percent or less, part of the deduction comes back as income.
- The heavy passenger vehicle cap. Section 179 is capped at $32,000 in 2026 for a vehicle rated over 6,000 and up to 14,000 pounds that is built mainly to carry passengers, unless it seats more than nine people behind the driver or meets another listed exception. The minivan on Florida’s contract is rated at 6,055 pounds. The cap limits Section 179 only, not special depreciation.
- The mileage rate. For 2026 it is 72.5 cents a mile through June 30 and 76 cents from July 1. You cannot use it for any vehicle when you run five or more at the same time.
- Lease or purchase. Publication 463 says you cannot deduct payments made to buy a vehicle, even if the contract calls them lease payments.
- TRAC leases. Some commercial vehicle leases carry a terminal rental adjustment clause, which raises or lowers your final payment by what the lessor gets when it sells the van. Federal tax law does not count that clause against lease treatment, as long as the deal otherwise qualifies as a lease and you sign a separate statement certifying that more than half the van’s use will be in your business (26 U.S.C. 7701(h)).
Which way saves more depends on your income, your state, and how long you keep the van. Plan it with your CPA before you sign. See NEMT business taxes and the mileage deduction calculator.
Lease terms to read before you sign
A business lease gives you fewer protections than a personal car lease. Federal Regulation M covers only leases to a person for personal, family, or household use, and it leaves out business leases by name (12 CFR 1013.2). On an open-end consumer lease, a shortfall at the end of more than three monthly payments is presumed unreasonable, and the lessor must win in court to collect the excess (12 CFR 1013.4). A lease signed by your NEMT company gets no such limit, so the contract is your only protection. Check these terms:
- Open-end or closed-end. In an open-end lease you owe the difference if the van sells for less than its estimated residual value. In a closed-end lease that risk stays with the lessor. A TRAC lease works like an open-end lease, because its final payment moves with what the van sells for.
- Mileage allowance and the charge per extra mile. Compare them with your real miles.
- Wear and damage standards. Get the written standard for the ramp, lift, floor, and seats.
- Consent to modify. Get written permission for any conversion, cameras, signs, or tie-downs you add.
- Early termination. SBA warns of steep early-termination penalties. NEMT work can end fast: MTM Health’s standard provider agreement, in the version Pennsylvania posts dated January 1, 2023, runs three years, lets either side end it on 30 days’ notice, and guarantees no minimum number of trips.
- Buyout price. SBA notes some leases let you buy the van at the end. Get the price, or the formula, in writing.
- Insurance and maintenance. Ask what coverage the lessor requires and whether any maintenance is included.
Financing a purchase
If you buy, match the loan to the van’s working life. SBA 7(a) loans can run up to 10 years for equipment, longer only when its useful life is longer. SBA caps variable 7(a) rates at the base rate plus 6.5 points for loans of $50,000 or less, 6.0 points for $50,001 to $250,000, 4.5 points for $250,001 to $350,000, and 3.0 points above $350,000.
A long loan lowers the payment but can outlast the van. Stretch the $63,693.90 loan above to six years at 9 percent and the payment drops to $1,148.12. After five years of payments you still owe $13,128.37 on a van Florida’s table plans to retire at five. For lenders, down payments, and the papers they want, see NEMT business loans.
Every van needs credentialing, owned or leased
The broker and state rules below allow leased vans. They check the registration, the insurance, and the van itself.
- Own or lease. Louisiana says a provider must own or lease its vehicles. The broker checks that each one is registered in the company’s name, and a leased van must meet the state’s insurance rules for leased vehicles (manual section 10.3, July 14, 2025).
- Insurance. If your auto policy is a scheduled policy, MTM Health’s standard agreement requires it to list each vehicle, and you must report additions and deletions to MTM right away.
- Inspection before use. Louisiana requires you to report each newly added vehicle to your broker, with its registration and certificate of insurance, so it can be inspected and credentialed before use. The rules apply to every vehicle before it carries a rider, so a short-term rental needs the same paperwork and inspection.
- No sharing. Louisiana bars NEMT providers from sharing vehicles, even between companies with the same owner.
- Records. Minnesota requires each vehicle record to name the person furnishing the vehicle when you do not own it (Minn. Stat. 174.30).
Build the insurance and inspection time into your start date for any new van. See NEMT insurance requirements.
How to decide, step by step
- Count your miles. Use your trip logs or broker volume to project miles per van per year.
- Get the broker’s limits. Ask for age, mileage, and equipment rules in writing.
- Price the same van three ways. Get a cash price, a loan quote, and a lease quote with the allowance, per-mile charge, fees, and buyout.
- Total each option over the years you will keep the van. Subtract a realistic resale value from the cash and loan totals.
- Check your cash. Keep enough for payroll, fuel, and insurance while claims are pending.
- Run the taxes with your CPA. Compare first-year depreciation with lease deductions for your income.
- Read the lease or loan contract. Look for open-end terms, early termination, modification consent, and prepayment penalties.
- Line up insurance and the broker inspection before the van arrives, so it can start earning in its first week.
Frequently asked questions
Is it cheaper to lease or buy a wheelchair van for NEMT?
Usually buying. SBA says the lifetime cost to buy is usually less than leasing, while a lease needs less cash or credit up front and can beat a high-interest loan. On a $70,771 ramp minivan, a 10 percent down payment plus five years of loan payments at 9 percent total $86,407.90. A five-year lease wins only if every lease payment and fee totals less than that, minus what you could sell the van for.
Can I deduct lease payments on a NEMT van?
Yes, the business part. IRS Publication 463 lets you deduct the part of each lease payment that is for business use, spread over the lease term if you pay in advance. It also says you cannot deduct payments made to buy a vehicle, even if they are called lease payments. Sole owners report vehicle lease costs on line 20a of Schedule C.
Can I take bonus depreciation or Section 179 on a leased van?
Not on the van itself. IRS Publication 946 says you generally cannot depreciate property you lease, because you do not own it. You can depreciate capital improvements you add, such as a lift you pay to install. If your lease is really a purchase in disguise, the IRS treats you as the owner, so ask your CPA to read the contract.
What happens if I drive over the mileage limit on a van lease?
You pay the lease's charge for each extra mile when you turn the van in. The charge is set in your contract, so get it in writing. At 20 cents a mile, 50,000 extra miles cost $10,000. A business lease is not covered by the federal consumer lease rules that limit end-of-lease charges on personal leases, so read the mileage and wear sections before you sign.
Can I use the IRS mileage rate for a leased NEMT van?
Yes, but only if you use it for the whole lease. The 2026 business rate is 72.5 cents a mile through June 30 and 76 cents from July 1. IRS Publication 463 bars the standard rate if you run five or more vehicles at the same time, and once you deduct actual expenses on a leased vehicle you cannot switch to the mileage rate for it.
Can I use a leased van for broker trips?
Yes, in the programs on this page. Louisiana's Medicaid manual says a provider must own or lease its vans, and the broker checks that each one is registered in the company's name and meets the state's insurance rules for leased vehicles. Minnesota's vehicle records allow for vans furnished by someone else. MTM Health's provider agreement, in the January 1, 2023 version Pennsylvania posts, says nothing about ownership, but a scheduled auto policy must list each vehicle.
How long should a NEMT van loan be?
No longer than the van will work. SBA 7(a) loans for equipment can run up to 10 years, but Florida's transit program plans for a converted minivan to serve 5 years or 200,000 miles. On a 6-year loan at 9 percent for $63,693.90, you still owe $13,128.37 after five years of payments. Rhode Island retires NEMT vans added after July 31, 2024 at 250,000 miles.