Starting a business
NEMT Business Loans in 2027: SBA Loans, Van Financing, and What Lenders Need
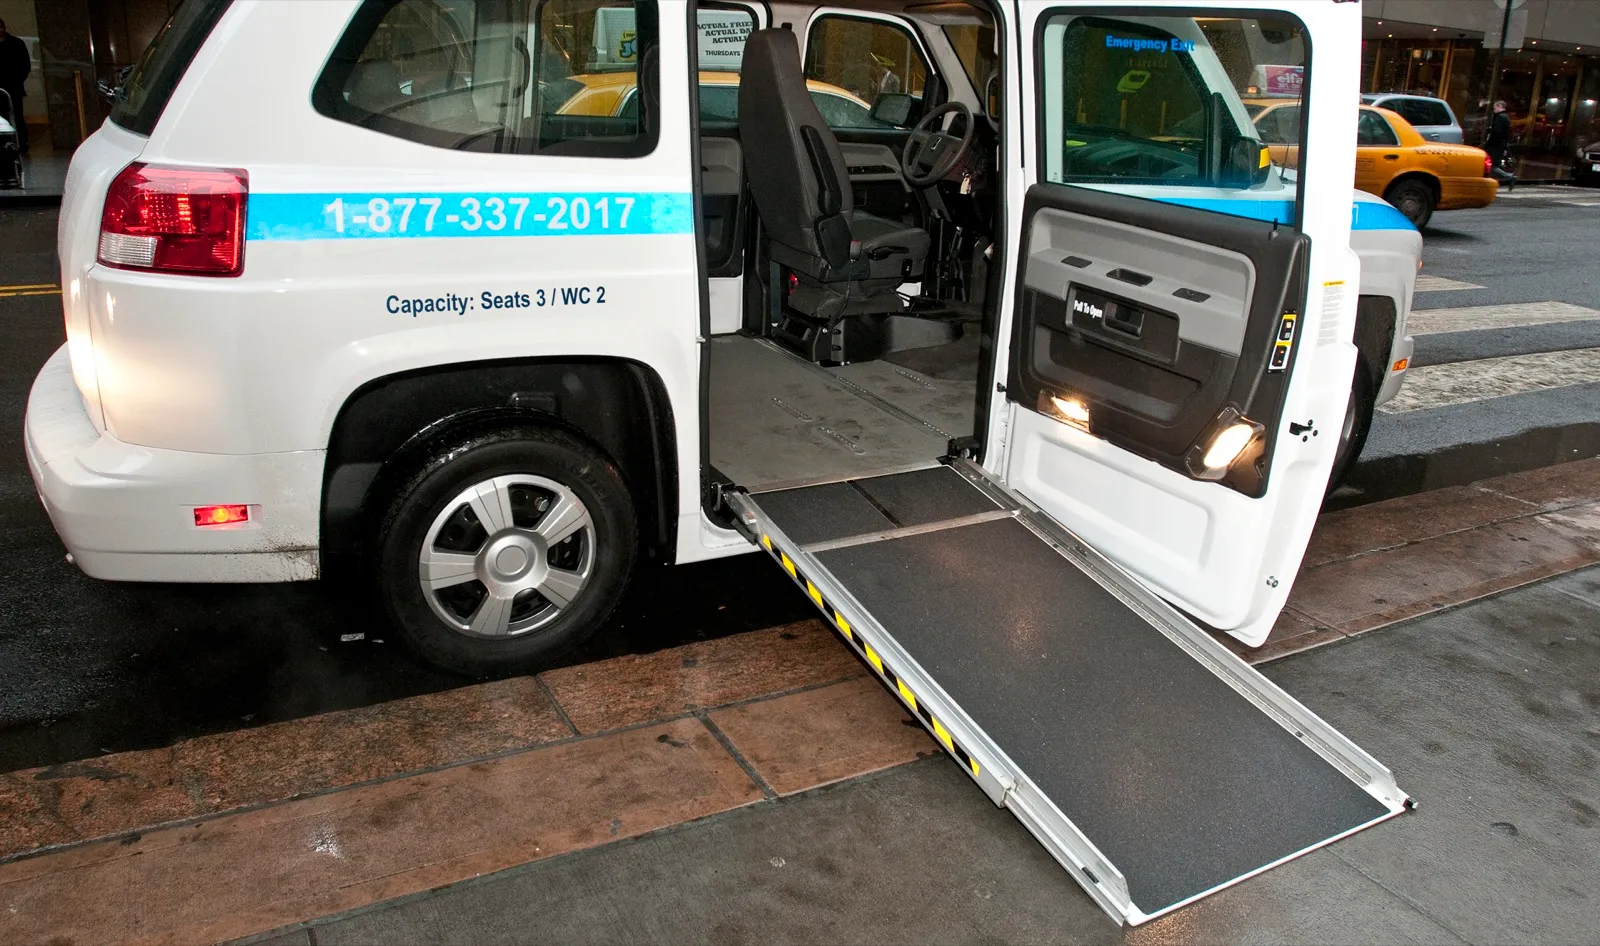

The main ways to fund a new NEMT company are an SBA 7(a) loan or microloan, a vehicle loan or lease, and the owner's cash. Under SBA's 7(a) rules as of October 1, 2026, a company open a year or less usually must put in 10 percent of its startup costs, every owner must be a U.S. citizen or national, and each 20 percent owner signs a personal guarantee.
- Bring cash. Standard and 7(a) Small loans to a company open a year or less need equity of at least 10 percent of the startup costs.
- Since March 1, 2026, SBA 7(a) and 504 loans require every owner and guarantor to be a U.S. citizen or U.S. national living in the United States.
- Lenders judge a new NEMT company on the owner's credit and a cash flow forecast, so back the forecast with real rates and payer approvals.
- SBA microloans lend up to $50,000 for a down payment, equipment, or working capital, repaid within seven years.
- State Medicaid payments cannot be paid to a factor, so plan cash for slow claims with savings or a line of credit.
A lender looks at a new NEMT company and sees three risks: a van that loses value, payers who pay weeks after the ride, and an owner with no track record yet. Your job is to answer each one before you apply. Below are the ways to borrow, starting with the ones that ask the least of a brand-new company, then what lenders check and the papers to bring.
The main ways to fund a NEMT company
Start with the total. The cost to start a NEMT business guide builds it line by line: the vehicle, insurance, fees, and the cash to run until payers pay you. Then match each piece of that total to the kind of money that fits it.
| Option | Best for | Size | Longest term | What a new company needs |
|---|---|---|---|---|
| Your own cash | The down payment and your cash reserve | What you have | None | Nothing, and SBA lenders require some of it |
| SBA microloan | A down payment, equipment, or working capital | Up to $50,000, about $13,000 on average | 7 years | A plan and a nonprofit intermediary lender near you |
| Vehicle loan or lease from a dealer, bank, or credit union | One van at a time | The van’s price | The lender’s policy | Credit, a down payment, and the van as collateral |
| SBA 7(a) Small | Vans, equipment, and startup working capital | $350,000 or less | 10 years for equipment | 10 percent equity, credit, and a forecast |
| SBA Express | The same uses, decided by the lender under its own SBA Express authority | $500,000 or less | 10 years | Credit and a forecast, from a lender with Express authority that sets its own equity rule |
| Standard SBA 7(a) | Several vans, a garage, or buying a company | $350,001 to $5 million | 10 years, 25 for real estate | Full documents and collateral where available |
| SBA 504 | A building or long-life equipment at a fixed location | SBA’s part is $25,000 to $5 million | 25 years for real estate | 10 percent down, 15 percent for a new business |
| CDFI loan | Owners banks turn down | The lender’s policy | The lender’s policy | A certified CDFI that lends in your area |
SBA amounts and terms are those in SOP 50 10 8.1, effective October 1, 2026. A 504 loan does not fit vans. It pays for buildings and for machinery with at least 10 years of useful life at a fixed location, and it cannot be used for working capital.
Two other sources are worth one call each. Community development financial institutions (CDFIs) are banks, credit unions, and loan funds certified by the U.S. Treasury to serve low-income communities, and Treasury posted its list of certified CDFIs as of September 17, 2026. Many states also run loan guarantee, loan participation, and collateral support programs funded by Treasury’s State Small Business Credit Initiative. Few grants go straight to a for-profit company, and grants for NEMT businesses explains which ones are real.
SBA 7(a) loans for a NEMT company: the rules as of October 1, 2026
SBA does not lend the money. It guarantees part of a loan from a bank or other lender, up to 85 percent of loans of $150,000 or less and 75 percent above that, and 50 percent on SBA Express loans. You apply to the lender. SOP 50 10 8.1 applies to every application that gets an SBA loan number on or after October 1, 2026.
A NEMT company is eligible if it runs for profit in the United States, is small, and cannot get the same credit on reasonable terms elsewhere. The size limit for special needs transportation (NAICS 485991) is $19.0 million in average yearly receipts, so almost every NEMT company qualifies.
Equity: at least 10 percent from you
SBA treats a company as a start-up if it has earned revenue from its intended work for one year or less. A standard or 7(a) Small loan to a start-up needs an equity injection of at least 10 percent of the total project costs: all the costs required to become operational, whatever the source of the rest. On SBA Express loans, the lender decides whether to require equity. These can count as equity:
- Cash you did not borrow, including a gift.
- A personal loan you repay from income outside the business. Salary the business pays you does not count.
- Debt on full standby, meaning no payments of principal or interest for the life of the SBA loan.
- A grant with no repayment or clawback terms during the loan.
For example, if it costs $80,000 to open with one van, insurance, fees, and working capital, you need at least $8,000 of equity in the deal.
The lender also checks the credit elsewhere test. It must show you cannot get the money on reasonable terms without SBA’s help, and it looks at the liquid assets of owners with 20 percent or more. SBA lets owners keep reasonable funds for medical costs, education, and retirement.
Who can own the company
Since March 1, 2026, and in SOP 50 10 8.1 from October 1, 2026, SBA 7(a) and 504 loans go only to businesses whose direct and indirect owners and required guarantors are all U.S. citizens or U.S. nationals with their main home in the United States. The SOP lists lawful permanent residents (green card holders), visa holders, refugees, people granted asylum, and DACA recipients as ineligible. An ineligible owner must give up all ownership before the loan number is issued, and SBA looks back six months. Naturalized citizens are eligible with no extra steps.
Guarantees, collateral, and life insurance
- Personal guarantee. Anyone who owns 20 percent or more, directly or indirectly, gives an unlimited full guarantee (SBA Form 148 or the lender’s own form).
- Collateral. For 7(a) Small loans of $50,000 or less, SBA requires no collateral. Above that, the lender takes a first lien on the assets the loan buys, such as the van. The lender need not take a lien on a vehicle worth $20,000 or less, or one that already has a lien. Standard 7(a) loans must be secured by available fixed assets, and a shortfall means a lien on personal real estate with at least 25 percent equity. SBA says a loan must not be declined only because collateral falls short.
- Life insurance. On a standard 7(a) loan that is not fully secured, a business that depends on one owner must carry life insurance on that owner for the shortfall.
Rates and terms
SBA caps variable rates at a base rate, usually prime, plus a set margin. The Federal Reserve reported prime at 7.00 percent for the week of September 21, 2026.
| Loan size | Maximum variable rate | With prime at 7.00% |
|---|---|---|
| $50,000 or less | Prime plus 6.5 points | 13.5% |
| $50,001 to $250,000 | Prime plus 6.0 points | 13.0% |
| $250,001 to $350,000 | Prime plus 4.5 points | 11.5% |
| Over $350,000 | Prime plus 3.0 points | 10.0% |
Equipment and working capital loans generally run 10 years at most, with the shortest term that fits the use. SBA also charges the lender an upfront guaranty fee, and the lender may pass it on to you. For loans approved from October 1, 2026, through September 30, 2027, the fee on loans longer than 12 months is 2 percent of the guaranteed part for loans of $150,000 or less and 3 percent for loans of $150,001 to $700,000. It is 0 percent on loans of $700,000 or less to businesses located in a rural area. The van loan calculator turns a rate and term into a monthly payment.
SBA microloans for a first van or startup costs
Microloans come from nonprofit intermediary lenders that SBA funds. As of September 2026, SBA says microloans go up to $50,000, average about $13,000, and carry rates generally between 8 and 13 percent. The rule, 13 CFR 120.707, adds limits:
- Each microloan must be repaid within seven years.
- Lenders generally should not lend more than $10,000 to one borrower.
- Above $20,000, you must show you cannot get credit elsewhere at comparable rates and have good prospects for success.
- The money can pay for working capital, supplies, furniture, fixtures, and equipment. It cannot pay off existing debt or buy real estate.
The intermediary makes every credit decision and sets the terms. SBA says its intermediaries have experience in lending and in management and technical help, which is useful if you have never run a company. At these limits, a microloan fits a down payment, a lift or ramp, or the first months of insurance better than a whole converted van.
Van loans and leases from dealers, banks, and credit unions
A dealer, bank, or credit union loan for one van uses the van as collateral. The terms are whatever the lender offers, so compare at least two written offers.
Business loans come with fewer consumer protections. Federal Truth in Lending rules do not apply to credit for a business purpose or credit to a company (12 CFR 1026.3), and federal consumer lease rules exclude leases for business purposes (12 CFR 1013.2). Ask for the rate, every fee, the payment schedule, and any prepayment penalty in writing.
SBA’s list of lease pros and cons, with the loan side for contrast:
| Leasing | Buying with a loan | |
|---|---|---|
| Cash up front | Less cash or credit needed | A down payment |
| Monthly cost | Shorter leases have higher payments | Spread over the loan term |
| Lifetime cost | Normally higher than buying | Interest and fees on top of the price |
| Taxes | Payments typically deductible, depreciation typically not | Depreciation and interest |
| Ending early | Can bring steep termination penalties | Pay off the balance |
SBA notes that a lease can cost less than a high-interest loan. Check any lease for a mileage cap, because NEMT vans pile up miles. Lease or buy NEMT vehicles compares the totals over five years.
What lenders look at when a NEMT company applies
Your personal credit. SBA says loan eligibility for a new business is typically based on the owner’s personal credit score. For 7(a) loans, the lender reviews the credit reports of every owner and guarantor and explains any problems.
Your experience. For a standard 7(a) loan, the lender’s write-up must describe the depth of your management experience in the industry or a related one, and who runs the business day to day. Put your NEMT, transit, or health care work history in the plan.
A forecast that covers the payments. A new company has no history, so the lender relies on your projections and their assumptions. A standard 7(a) loan needs debt service coverage of at least 1.15 within two years of funding. A 7(a) Small loan needs 1.10 within one year. Coverage is your cash flow before interest, taxes, depreciation, and amortization, divided by all your loan payments.
| Example | Math | Result |
|---|---|---|
| Loan | $48,000 at 9% for 60 months | $996.40 a month |
| Cash flow needed at 1.15 | $996.40 × 1.15 | $1,145.86 a month |
| Cash flow needed at 1.10 | $996.40 × 1.10 | $1,096.04 a month |
These are example numbers, not a loan offer. The break-even calculator shows how many trips that takes.
Who pays you, and when. Base your trip rates on your state’s fee schedule or your broker’s rate sheet, not a guess. Lenders also read the contract terms. MTM Health’s standard agreement, in the version Pennsylvania posts dated January 1, 2023, guarantees no minimum number of trips, lets either side end it on 30 days’ written notice, pays uncontested invoices within 30 days of electronic submission, and refuses claims sent more than 90 days after the ride. Build the time from ride to claim to payment into your forecast. See how long Medicaid takes to pay.
Enough cash to reach the first payments. For a standard 7(a) loan, the lender must analyze whether you have enough working capital for at least the next 12 months. Show the months of payroll, fuel, insurance, and loan payments you can carry, using NEMT cash flow and the cash reserve calculator.
Insurance. For a standard 7(a) loan, the lender must address business hazard and liability coverage. Get quotes at your broker’s limits before you apply. MTM’s Pennsylvania agreement asks for a $500,000 combined single limit of auto liability and $500,000 of general liability per occurrence.
Documents to prepare before you apply
SBA’s SOP sets the core list for 7(a) loans, and smaller loans need less of it. The last three rows are what any lender to a NEMT company will want to see. Have all of it ready.
| Document | What it shows |
|---|---|
| Business plan | Your market, payers, fleet, and people. SBA’s Lender Match checklist says most lenders expect one for startup funding. |
| Monthly forecast for the first 12 months or more, with assumptions | That the trips can cover the payments |
| SBA Form 1919, Borrower Information Form | The company, its owners, the loan request, and existing debts |
| SBA Form 413, Personal Financial Statement, for each 20 percent owner and guarantor | Your assets and debts, signed within 90 days |
| IRS Form 4506-C or Form 8821 | Permission for the lender to pull your tax transcripts |
| Business financial statements or tax returns for up to 3 years, and interim statements within 120 days | History, if the company already runs |
| A debt schedule | Every loan and lease you already pay |
| Itemized vehicle and equipment quotes | Exactly what the loan buys |
| Your office or garage lease | A fixed cost the forecast must cover |
| Two recent months of business bank statements | Debts not on the schedule. 7(a) Small lenders review them if you already operate. |
| Formation papers, EIN letter, and NPI record | Who owns the company and how it is registered |
| Medicaid enrollment approval, broker agreements, and facility contracts | Where the trips will come from |
| Insurance quotes, licenses, and permits | That you can legally run on day one |
The NEMT business plan template has sections for payers and contracts, fleet, drivers, startup costs and funding, and the first 12 months of cash.
How to get a NEMT business loan, step by step
- Price everything. List the van, the lift or ramp, insurance, fees, and the running costs until your first payments arrive.
- Set aside your equity. Plan on at least 10 percent of the total in cash for an SBA loan, and keep a reserve on top of it.
- Check your credit. Pull your own reports and fix errors before a lender sees them.
- Get free help. SBA’s resource partners, including Small Business Development Centers, SCORE, Women’s Business Centers, and Veterans Business Outreach Centers, offer free or low-cost counseling and training.
- Line up your approvals. Start Medicaid enrollment and broker credentialing, and get insurance quotes, so the plan rests on real numbers. See how to become a Medicaid transportation provider.
- Find lenders. SBA’s Lender Match asks a few questions, which SBA says take as little as five minutes, and sends a summary of interested lenders two business days later. As of September 2026, more than 800 lenders take part. It is not an application and guarantees no loan. Also call a microlender and a CDFI near you.
- Compare offers. Ask each lender for the rate, minimum credit score, cash flow rules, fees, prepayment penalties, grace periods, and when it could demand full repayment.
- Close and keep your reserve. Loan payments start on the lender’s schedule, even if your first claims have not been paid.
Financing to avoid or handle with care
- Factoring Medicaid claims. Federal rule 42 CFR 447.10 bars a state Medicaid program from paying for your services to or through a factor, a company that advances money on claims you sell or assign to it. A billing service may receive payments in your name only if its fee is tied to the cost of billing, is not a percentage of what it bills or collects, and does not depend on collecting.
- Assigning broker payments without notice. MTM Health’s Pennsylvania agreement bars assigning the agreement without MTM’s written consent, and requires written notice at least 30 calendar days before any payment you assign to a third party. Other brokers have their own clauses.
- Paid middlemen and bridge loans. SBA says you do not need to pay a middleman to get an SBA loan, and warns that a high-interest bridge loan while you wait for SBA money is often a debt trap. Anyone who packages or refers your SBA loan for a fee must disclose it on SBA Form 159.
- A loan that outlasts the van. Keep the term no longer than you expect to run the vehicle. The van loan calculator shows how much more interest a longer term costs.
If you plan to buy an existing NEMT company instead of starting one, SBA’s change of ownership rules add a business valuation and other conditions. How to sell a NEMT business covers them from the seller’s side.
Frequently asked questions
Can I get an SBA loan to start a NEMT business?
Yes, if your company meets SBA's rules and a lender approves it. A NEMT company is small for SBA purposes up to $19.0 million in average yearly receipts (NAICS 485991). Under SOP 50 10 8.1, effective October 1, 2026, a company open a year or less must put in at least 10 percent of project costs on a standard or 7(a) Small loan, and its forecast must show it can cover its loan payments. The lender makes the decision, not SBA.
How much money do I need to put down on a NEMT loan?
For a standard or 7(a) Small loan to a start-up, at least 10 percent of all the costs to become operational, whatever the source of the rest. Cash you did not borrow, a gift, a grant you never have to repay, and seller debt with no payments for the life of the loan can count. SBA Express lenders decide for themselves. SBA 504 loans need 10 percent, or 15 percent for a new business. Dealers, banks, and microlenders set their own down payments.
Can a green card holder get an SBA loan for a NEMT company?
Not a 7(a) or 504 loan. Since March 1, 2026, and in SOP 50 10 8.1 from October 1, 2026, every direct and indirect owner and every required guarantor must be a U.S. citizen or U.S. national whose main home is in the United States. Lawful permanent residents, visa holders, and DACA recipients are listed as ineligible. Banks, credit unions, and dealers lending without an SBA guarantee set their own rules.
Do I need a broker contract before I apply for a loan?
SBA does not require one, but a new company's loan rests on its forecast, and the lender must see the assumptions behind it. A Medicaid enrollment approval, a signed broker agreement, or a facility contract is the strongest support for your trip count and rates. Lenders may still discount broker work: MTM Health's standard agreement, in the version Pennsylvania posts dated January 1, 2023, guarantees no minimum number of trips.
What credit score do I need for a NEMT loan?
Your lender sets it, so ask each lender for its minimum. SBA says loan eligibility for a new business is typically based on the owner's personal credit score, and that poor credit history is one of the main reasons small business loan applications are declined. For 7(a) loans, the lender must review the personal credit reports of the owners and guarantors and explain any problems in its write-up.
Can I borrow against my Medicaid or broker payments?
Be careful. Federal rule 42 CFR 447.10 bars a state Medicaid program from paying for your rides to or through a factor, a company that advances money on claims you sell or assign to it. For trips billed to a broker, read your agreement: MTM Health's Pennsylvania agreement requires written notice at least 30 calendar days before any payment you assign to someone else. Ask your state before pledging Medicaid receivables.
Is it better to lease or finance a wheelchair van?
It depends on your cash and the offer. SBA says a lease needs less cash or credit up front, sometimes includes maintenance, and its payments are typically tax deductible, but the lifetime cost is normally higher and depreciation of a leased asset typically is not deductible. SBA also notes a lease can cost less than a high-interest loan. Compare the total you pay over the years you will keep the van.
Official resources
- SBA: Lender Match
- SBA: 7(a) loans
- SBA: Microloans
- SBA: List of microlenders
- SBA: 504 loans and certified development companies
- SBA: Find free local business counseling
- SBA: Form 1919, Borrower Information Form
- SBA: Form 413, Personal Financial Statement
- U.S. Treasury CDFI Fund: Certified CDFIs
- U.S. Treasury: State Small Business Credit Initiative programs